Geopolitical Risk in 2027: What Davos Decision-Makers See Before Markets Do
By The Davos Collective · 13 September 2026 · 8 min read
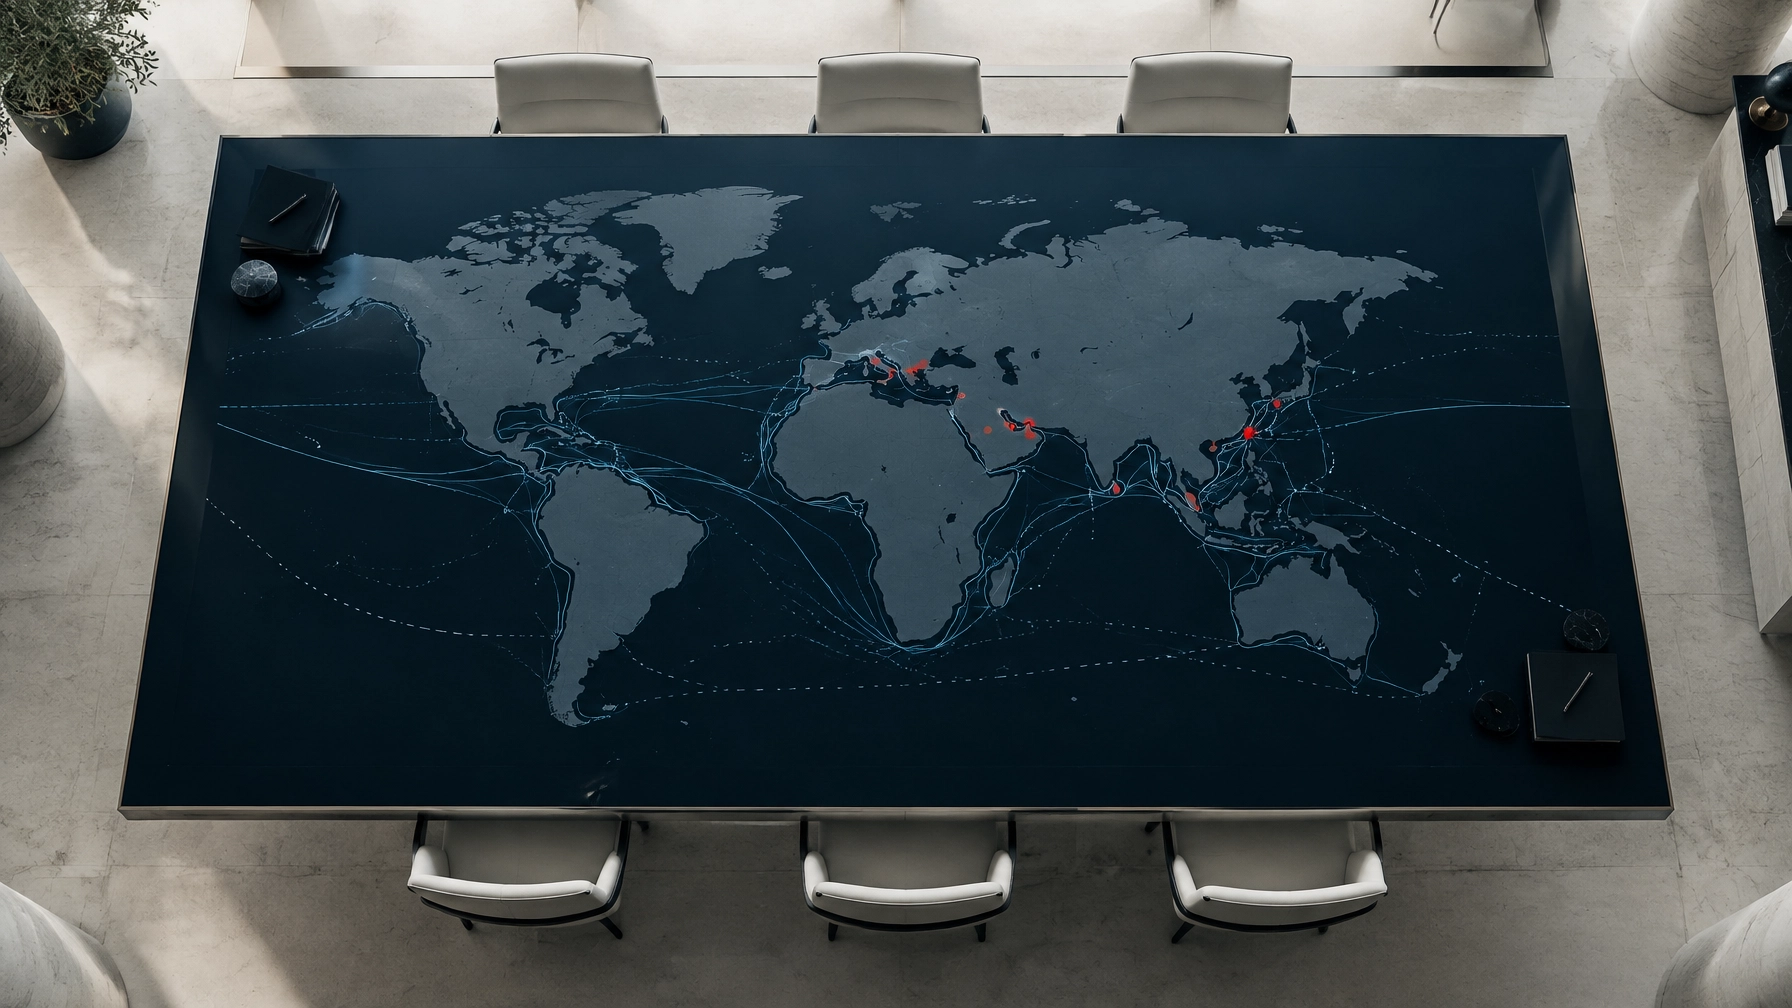
The most consequential signals for 2027 are not emerging from a single conflict or market indicator. They are visible in the interaction between trade policy, supply-chain design, energy security, defence spending, technology controls and the gradual fragmentation of the global operating environment.
Public discussions around the Davos ecosystem increasingly treat geopolitics as a structural macroeconomic force rather than an occasional shock. The distinction matters. A temporary crisis can be hedged, absorbed or priced. Structural geopolitical risk changes the assumptions behind investment, expansion, sourcing, financing and corporate strategy.
The World Economic Forum’s Global Risks Report 2026 identifies geoeconomic confrontation as the leading near-term global risk. The IMF’s July 2026 World Economic Outlook Update projects global growth of 3.4% in 2027, while warning that trade fragmentation and geopolitical tensions could weaken the baseline.
The message for executives and investors is direct: 2027 is likely to be defined less by a return to normality than by the institutionalisation of uncertainty.
1. Geoeconomic confrontation becomes the primary risk channel
Geopolitical competition is increasingly expressed through economic instruments.
Tariffs, export controls, sanctions, investment restrictions, industrial subsidies, technology licensing rules and critical-mineral policies are now central tools of statecraft. These measures can be introduced without military escalation, yet they can materially affect corporate earnings, supply continuity and asset valuations.
This is the first major signal for 2027. Governments are not merely responding to geopolitical risk; they are actively using economic interdependence as leverage.
For business leaders, the relevant question is no longer whether a market is commercially attractive in isolation. It is whether access to that market, its technology, capital, infrastructure and suppliers can remain politically viable.
The implications include:
- Higher compliance costs across jurisdictions
- More frequent changes to trade and investment rules
- Greater scrutiny of ownership and technology transfer
- Reduced reliability of cross-border assumptions
- Higher premiums for strategic inputs
- More complex decisions around market entry and capital allocation
Markets may continue to focus on tariffs as discrete policy events. Decision-makers in the Davos ecosystem are assessing the wider system: whether the architecture of global trade is becoming permanently more transactional.

2. Growth may remain positive while economic confidence deteriorates
The 2027 global growth outlook is not necessarily a recessionary one. The IMF’s current baseline anticipates a moderate improvement from 2026. World trade is also expected to recover from its 2026 pace.
That headline stability may conceal a more difficult operating environment.
Growth can remain positive while businesses experience lower visibility, weaker productivity, higher insurance costs and more volatile demand. Fragmentation increases the cost of doing business even when aggregate output continues to expand.
This creates a divergence between macroeconomic forecasts and executive confidence. A country may report resilient GDP growth while companies delay investment because they cannot determine whether a new tariff, regulatory measure or diplomatic dispute will alter the economics of a project.
The central 2027 economic trend is therefore not simply slower or faster growth. It is the declining reliability of historical relationships.
Past assumptions about trade elasticity, regional specialisation, low-cost sourcing and stable capital flows are becoming less dependable. Business planning increasingly requires multiple operating scenarios rather than a single forecast.
This is where geopolitical risk analysis becomes operational. It must connect political developments to:
- Revenue exposure
- Supplier concentration
- Currency volatility
- Financing conditions
- Energy prices
- Insurance availability
- Regulatory obligations
- Strategic inventory requirements
The distinction between political analysis and economic analysis is narrowing. The most useful outlooks treat them as one integrated system.
3. Supply-chain resilience moves from preference to policy
The efficiency model of globalisation relied on concentration. Production was placed where costs were lowest, inventories were minimised and supply networks were optimised for scale.
The resilience model of 2027 will rely on optionality.
The shift is already visible in semiconductors, energy systems, pharmaceuticals, food security, telecommunications and critical minerals. Governments are encouraging domestic production, regional manufacturing and trusted-partner networks. Corporations are reassessing dependencies that previously appeared commercially rational but politically exposed.
This does not mean globalisation ends. It means globalisation becomes more conditional.
The strongest companies will not necessarily abandon international supply chains. They will build a clearer understanding of where substitution is possible, where stockpiling is justified and where political alignment matters more than marginal cost.
Strategic autonomy will remain a dominant concept in Europe and among middle powers. Energy, defence, digital infrastructure and critical technologies will receive particular attention because they combine commercial value with national-security significance.
For investors, this points towards sustained capital expenditure in:
- Grid infrastructure and energy storage
- Defence and dual-use technologies
- Semiconductor capacity
- Cybersecurity
- Logistics and supply-chain software
- Critical-mineral processing
- Domestic manufacturing capacity
- Data-centre and digital infrastructure
The investment case is not based solely on demand growth. It is based on the political willingness to fund resilience.

4. Energy remains the fastest transmission mechanism
Geopolitical risk reaches markets most quickly through energy.
A disruption to production, transport routes or export infrastructure can affect inflation, interest rates, industrial margins and consumer confidence within weeks. Oil and gas remain significant channels, but electricity networks, shipping capacity, refined products and critical energy technologies are also becoming strategically important.
The 2027 outlook therefore requires more than monitoring conflict zones. It requires monitoring the infrastructure that connects them to global markets.
Key indicators include:
- Changes in shipping insurance premiums
- Disruptions around strategic maritime corridors
- Export restrictions on energy inputs
- Inventory levels and spare production capacity
- Regional electricity constraints
- Investment in energy interconnections
- The pace of defence and infrastructure spending
An energy shock would not affect every economy equally. Import-dependent countries would face higher inflation and weaker external balances, while producers could benefit from higher revenues but face political and logistical risks of their own.
The broader signal is that energy transition and energy security are no longer separate agendas. In 2027, capital allocation in renewables, grids, nuclear power, storage and conventional energy will increasingly be evaluated through the lens of strategic resilience.
5. Conflict risk remains regional, but the consequences are global
The principal geopolitical flashpoints entering 2027 remain concentrated in a limited number of theatres. Their economic effects are not.
The war in Ukraine continues to shape European security, defence expenditure, sanctions policy and energy strategy. Conflicts in the Middle East retain the potential to affect energy markets, shipping routes and regional diplomatic alignments. Tensions in East Asia remain critical for semiconductor supply, maritime trade and the broader relationship between the United States and China.
A conflict does not need to become global to become globally significant.
Its effects can travel through:
- Shipping delays
- Commodity prices
- Refugee movements
- Sanctions exposure
- Cyber operations
- Insurance markets
- Fiscal spending
- Currency movements
- Technology restrictions
This is why market participants can underestimate geopolitical risk even when they are aware of the underlying events. The first-order event may appear contained, while the second-order effects accumulate across sectors and jurisdictions.
The appropriate framework is not prediction. It is exposure mapping.
Executives should identify which geopolitical developments could alter their cost base, operating permissions, customer access or financing assumptions. Investors should distinguish between assets exposed to immediate disruption and those exposed to longer-term policy repricing.

6. Information disorder amplifies policy and market volatility
Misinformation, disinformation and societal polarisation remain important because they accelerate political reactions.
In a more fragmented environment, public narratives can influence sanctions, regulation, elections, consumer behaviour and corporate reputation. A contested event can produce policy consequences before facts are established, especially where national security or identity is involved.
For companies, this creates a new category of strategic exposure. Reputation risk can become regulatory risk. Regulatory risk can become market-access risk.
Decision-makers should therefore monitor not only formal policy but also the narrative environment surrounding it. The speed of public mobilisation, the involvement of state-linked actors and the alignment of political messaging across jurisdictions can indicate whether an issue is likely to escalate.
The signal for 2027 is a shorter distance between information disruption and economic consequence.
What Davos intelligence should provide in 2027
Davos intelligence is most useful when it identifies patterns across institutions, sectors and regions before they appear in conventional market data.
The relevant indicators include:
- Which risks receive sustained attention rather than temporary visibility
- Which sectors increase their presence and policy engagement
- Which governments coordinate around common strategic priorities
- Which issues move from private discussion to public language
- Which corporate investments indicate preparation for disruption
- Which regulatory changes convert geopolitical concerns into operating constraints
This is not a prediction that every concern discussed in Davos will materialise. It is a method for detecting convergence.
When governments, investors, executives and policy professionals begin using similar language around resilience, autonomy, security or fragmentation, the language itself becomes an indicator. It suggests that expectations are changing before financial data fully reflects the shift.
Conclusion: the 2027 baseline is managed fragmentation
The most credible 2027 outlook is neither systemic collapse nor a return to the pre-fragmentation global economy.
It is managed fragmentation: continued international commerce under stricter political conditions, more regional supply networks, higher strategic spending and recurring shocks to trade, energy and capital flows.
Executives and investors should treat geopolitical risk as a core planning variable. The relevant discipline is not forecasting every crisis. It is identifying where political change can alter economic outcomes before those changes are fully priced.
The Davos ecosystem is not a single authority and does not produce a single consensus. Its value lies in the concentration of decision-makers, institutions and capital around emerging global risks.
The Davos Collective provides independent intelligence on that ecosystem and is not affiliated with the World Economic Forum. That separation enables analysis of the networks, conversations and decision-makers shaping global economic and political discourse without institutional alignment.
2027 will reward institutions prepared for political uncertainty as a permanent economic condition.